

Principal®

- 2.32K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Principal® from Appgk
Managing money is rarely difficult because people do not care. It is difficult because financial tasks are spread across different moments: checking a balance before a purchase, reviewing retirement progress after work, or remembering to make a small adjustment when a goal changes. Principal® is designed to bring that kind of financial check-in to a phone. After spending time with it, I found its most useful quality is not simply having account information in a mobile format. It is the way the app can turn a quick glance into a more regular habit of staying aware of long-term goals.
This is a free finance app from Principal Financial Group, Inc., intended for everyone and available on Android. It has been around since March 1, 2019, and the current release is version 4.0.146. Its average rating sits at 4.7 from around 44 thousand ratings, while the app has passed one million installs. Those figures suggest that it has become a familiar tool for many Principal customers, but popularity alone does not make a financial app suitable for every person. The important question is whether its account-focused approach fits the way you actually manage money.
Why the mobile goal check matters
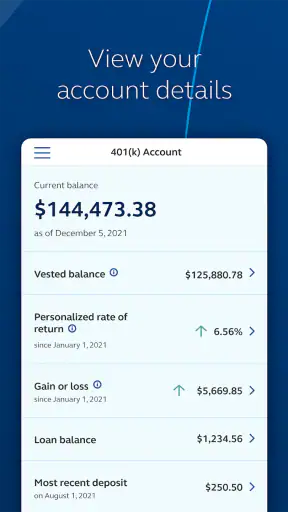
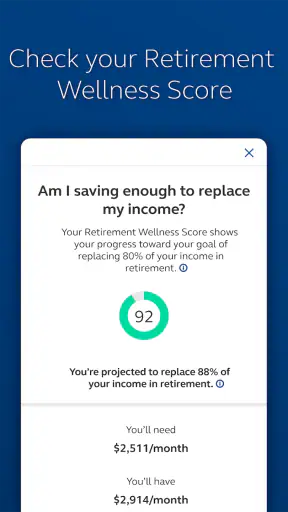
The central capability I noticed is the ability to keep financial goals within reach while away from a desktop. That sounds modest, but it changes the timing of financial decisions. Instead of waiting for a monthly review, I can use a spare minute to see where things stand, think about whether my current choices still make sense, and return to everyday spending with better context.
That is especially relevant for people whose Principal accounts are connected to workplace savings or other long-term planning. Long-term finances are easy to postpone because the results are not immediate. A mobile view does not solve every planning problem, but it lowers the effort needed to stay engaged. The difference is between saying “I should check that later” and actually looking while the question is still fresh.
Best Parts of Principal®
Things to Keep in Mind About Principal®
The real strength is the shorter distance between intention and action. If I am already thinking about a financial goal, opening the app is more practical than finding a computer, locating the right page, and trying to remember what I wanted to review. That convenience can make periodic attention more realistic, particularly for someone who does not want to build a detailed spreadsheet.
There is also a psychological benefit to seeing financial information in the same place where I handle other daily tasks. A phone is always nearby, so the app works best as a prompt for small, repeatable check-ins rather than as a replacement for serious financial planning. I would not treat a quick mobile view as a complete retirement strategy, but I do think it can help prevent long stretches of complete inattention.
News and Features Related to Principal®

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What the app feels like in ordinary use
My preferred way to use Principal® is in short sessions with a clear purpose. I might open it before changing a household budget, after receiving a pay-related update, or during a quiet moment when I want to confirm that a long-term goal is still on my radar. This approach keeps the app from becoming another stream of information to monitor constantly.
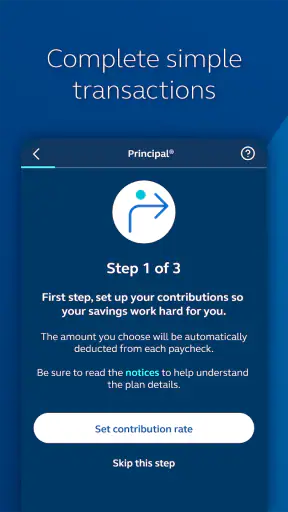
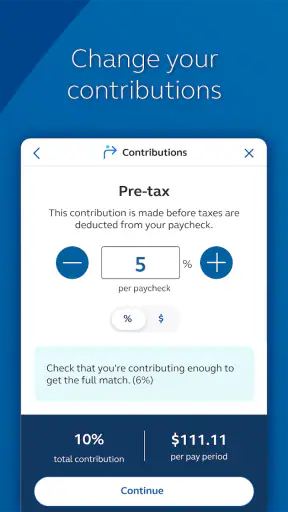
The experience is more useful when I already know what I want to check. A focused question such as “Do I need to review my current contribution?” is easier to handle than opening the app without a plan and expecting it to tell me what to do. In that sense, the app supports informed attention rather than replacing personal judgement.
Don't want to read the full review?
For a first-time user, the most important step is to establish a simple routine. I would begin by signing in, identifying which account or goal matters most, and deciding when a review makes sense. A short check after a regular financial event is more sustainable than opening the app repeatedly throughout the day. This is one of the less obvious lessons of a mobile finance tool: convenience helps only when it is attached to a habit.
Another practical point is to separate viewing from decision-making. A balance or progress view can tell me what is happening, but it does not automatically explain whether a change is appropriate for my income, debts, emergency savings, or time horizon. I would use the app to gather current information, then consider the wider household picture before making a meaningful adjustment.
Screenshots
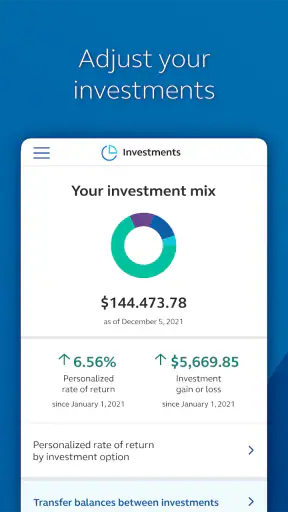
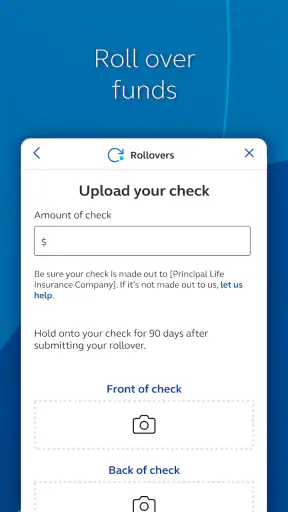
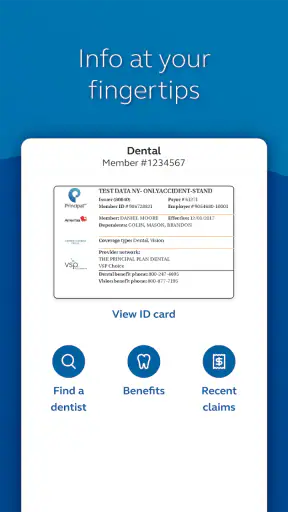
A realistic everyday scenario
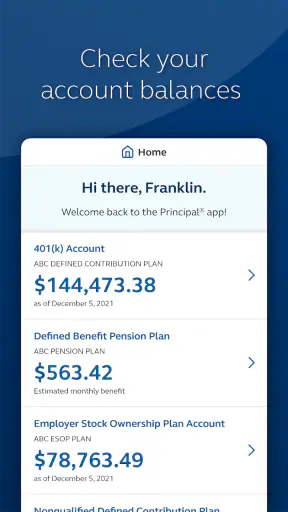
Imagine a worker reviewing the monthly budget on a Sunday evening. The household has had a few unusual expenses, and the person is wondering whether a long-term contribution should be changed temporarily. With Principal® on the phone, they can first check the relevant account information instead of relying on memory. That quick review may show that the better choice is to leave the long-term plan alone and reduce a discretionary expense elsewhere, or it may confirm that a larger conversation is needed.
The app is valuable in this situation because it provides a starting point at the moment the question arises. Without mobile access, the person might postpone the review until the question disappears into a busy week. With the app, they can at least replace guesswork with a current view. The app does not make the decision for them, and that is important: its role is to make the decision better informed.
A second useful scenario is preparing for a conversation with a partner. Rather than discussing vague intentions, I can review the information first and bring a more concrete question to the conversation. That makes the app a quiet preparation tool, not just a place to look at numbers. It can help turn “we should do something about our future” into “which part of our plan should we examine first?”
Where it fits among familiar alternatives
Compared with a spreadsheet, Principal® is less flexible but more convenient for checking information tied to the provider. A spreadsheet can combine rent, debts, cash savings, investments, and household goals in one custom model. The app is better suited to quickly reviewing Principal-related information without maintaining formulas or manually updating figures. I would choose the spreadsheet for a complete household forecast and the app for a current, provider-centered check.
Compared with a general budgeting app, its focus is narrower. Budgeting tools are usually strongest when I want to categorize spending across banks, cards, bills, and cash flow. Principal® makes more sense when my immediate concern is a financial goal or account held within the Principal environment. Someone looking for one dashboard across many unrelated institutions may prefer a broader aggregator, while someone mainly monitoring a Principal-based plan may find that broader setup unnecessarily busy.
Compared with using a desktop website, the mobile app wins on immediacy. A larger screen can be more comfortable for detailed comparisons, document work, or extended planning. The phone is better for a quick status check and for keeping financial awareness from being tied to a particular room or computer. I see the two formats as complementary rather than interchangeable.
What I would watch before relying on it
The same focus that makes the app approachable can also feel limiting. If I want a complete picture of my financial life, a provider-specific app is unlikely to be enough on its own. I still need another method for tracking everyday spending, debts, cash reserves, and goals outside the Principal relationship. That is not a flaw in the app’s basic purpose, but it is an important boundary.
There is also a risk of overreacting to short-term changes. Mobile access makes it easy to check information frequently, but frequent checking can encourage emotional decisions when markets or account values move. I would avoid treating every change on the screen as a reason to alter a long-term plan. The app makes information easier to reach; it does not make every reaction wise.
Security and privacy deserve the same attention as convenience. I would use a strong device lock, keep the operating system current, and avoid signing in on a shared phone. Those are practical habits for any finance app, but they matter more when the application gives direct access to personal financial information. I would also make sure I understand which account I am viewing before acting, especially if several goals or plans appear in the same session.
Another point is that the usefulness of a finance app depends on the quality of the user’s routine. Someone who wants detailed coaching, extensive cross-account analysis, or hands-on financial advice may find this experience too focused. Someone who only wants a quick way to remain connected to a Principal goal may appreciate that it does not force a full budgeting system into every visit.
Small workflows that make it more useful
I found three habits more valuable than simply opening the app at random. First, I would use it immediately before a planned financial conversation, so the discussion starts with current information. Second, I would pair a check-in with an existing monthly routine, such as reviewing bills, rather than creating a separate reminder that is easy to ignore. Third, I would write down the question I want answered before opening the app; this reduces aimless checking and makes the short session more productive.
A fourth habit is to record the reason for any important change outside the app. If I adjust a contribution or make another significant decision, noting whether the reason was a salary change, a new obligation, or a temporary budget problem can prevent confusion later. The mobile screen shows the current position, while a simple personal note preserves the context behind the decision.
I would also avoid judging the app by how well it handles a task it was never meant to lead. It is not my first choice for building an all-purpose spending plan. Its value is strongest when the task begins with a Principal account or goal and I need a convenient way to stay connected to that part of my finances.
Who will benefit most
This app is a strong match for Principal customers who want easier access to their financial goals without turning every review into a desktop project. It should also suit people who prefer brief, regular check-ins over elaborate financial software. The free price removes a common barrier to trying it, and the Everyone age rating makes it broadly accessible, although younger users may still need an appropriate account relationship and adult guidance for serious financial decisions.
I think it is particularly useful for busy workers who have good intentions but struggle to make time for financial maintenance. A short mobile session can fit between errands or during a commute break, provided the user is stationary and able to focus. It is also helpful for people who already understand the basics of their plan and mainly need a convenient way to stay aware of it.
I would be more cautious about recommending it as the only financial tool for someone with several institutions, complicated debt, irregular income, or a strong need for detailed forecasting. That person may be better served by combining the app with a full budget system, a spreadsheet, or professional advice. The app can still be one useful piece, but it should not be mistaken for a complete financial command center.
My final take on the mobile experience
After using Principal® as a focused finance companion, I came away with a clear impression: its best contribution is making long-term financial attention easier to repeat. It does not turn a complicated financial life into a single tap, and I would not use it as a substitute for broader planning. What it does well is put a relevant account or goal close at hand when I need to check my direction.
The app’s high average rating and large user base show that many people find this approach useful, but my recommendation is still conditional. Choose it if your financial activity is centered on Principal and you want convenient mobile access. Pair it with a broader budgeting method if you need a complete household view. Skip it as your primary tool if your main goal is detailed spending analysis across many providers.
For me, the deciding benefit is simple: the app makes it easier to look before guessing. Used with a clear question, a sensible schedule, and some restraint around major decisions, it can turn financial goals from something I intend to revisit into something I actually remember to review.
Principal® FAQ
What is Principal® and what can I use it for?
Principal® is a digital application designed to help users access and manage its available services from a mobile device. Depending on the version and region, it may provide account-related tools, personalized information, notifications, and other features in one place. Before downloading, check the official store description to confirm that the functions offered match your needs and are available in your country.
Is Principal® free to download and use?
Principal® can generally be downloaded without an upfront charge, but some services or features may depend on your account, subscription, investment, plan, or regional availability. Downloading the app does not necessarily mean that every function is free. We recommend reviewing the official pricing information, terms of service, and any applicable fees before registering or submitting personal or financial information.
Is Principal® safe for personal and account information?
Principal® may request sensitive details such as your name, email address, login credentials, identification information, or account data in order to provide its services. Use only the official Android or iOS store listing and keep the app updated. Review its privacy policy carefully, enable device security features, avoid sharing passwords, and contact official support if you notice suspicious activity or an unexpected sign-in.
What devices are compatible with Principal®?
Compatibility depends on the operating system, device model, available storage, and the minimum Android or iOS version required by the current release. Older phones may not support every feature or may provide a less reliable experience. Before installing Principal®, open its official store page and verify the listed requirements, developer name, permissions, recent update date, and whether the application is offered in your region.
Do I need an account to use Principal®?
Many of Principal®’s useful functions may require users to create an account or sign in through an existing service account. Registration can involve identity verification and acceptance of specific terms, particularly when the app handles confidential or financial information. Some basic content may be visible without signing in, but the exact access level can vary according to your location and the version installed.











